When you own an asset, you have a claim on any value that it produces, such as through direct cash flow or an eventual sale. That asset may also appreciate over time while debt repayment can steadily increase the portion of its value that belongs to you.
That’s different from something like income, where compensation is earned in exchange for time, labor, or expertise. However, that doesn’t mean income is a bad thing.
If you’re like many aspiring entrepreneurs, income is critical to your long-term success. A strong salary provides the security and capital you need to save, invest, and prepare for ownership. But the sum of your work and expertise will always benefit an asset owned by someone else — unless you are the owner.
Business ownership fundamentally changes the relationship between work, income, and wealth. All paths to ownership carry some level of risk and uncertainty, but the right approach can offset many of those challenges before capital is committed.
In this guide, you’ll learn:
- How ownership builds wealth differently from earned income
- How the Four Levers of Return generate wealth through ownership
- How business assets allow wealth to compound over time
- How the risks of ownership can affect wealth creation
Read the first chapter of Buy Then Build, free
Walker Deibel’s book on buying an existing business.
Get the free chapterWhat it takes to buy a business
Before any of the levers below start working for you, there’s a floor you have to clear. Buying a business isn’t something you back into with no preparation, and it isn’t reserved for people with millions in the bank. Here’s what it actually takes:
- Cash for a down payment and transaction costs. Debt-backed deals typically require 10-30% down (U.S. buyers can get it down to 10% with an SBA loan), plus closing costs and legal fees on top of that.
- Liquidity beyond the down payment. You need a cushion for day-to-day operations and the unexpected expenses that show up in the first year of owning anything.
- A multi-year commitment. These levers realize value over years, not months. If you’re looking for something you can turn around quickly, this isn’t the vehicle.
- Real experience or a credible plan. Lenders and sellers both want to see that you can actually run what you’re buying, not just that you can afford it.
- Financing, and usually a personal guarantee. Unless you’re paying cash, SBA-backed acquisitions require you to personally guarantee the loan.
None of this is meant to scare you off. It’s meant to be honest about the minimum requirements you need when pursuing asset ownership, so the rest of this piece makes sense in context.
How ownership turns work into wealth
Compensation and ownership solve two different problems, and it’s easy to blend them together because both eventually show up as a number in a bank account.
Compensation pays you for the value you create, in the moment you create it. When you stop working, the payments stop. The value you created is still there, but you don’t have a claim on it anymore. Instead, it belongs to whoever owns the business or platform where you built it.
Ownership doesn’t pay you for the work itself. It gives you a claim on whatever the work produces, for as long as you hold that claim.
That distinction is the entire reason the two paths end up in such different places over time.
When people ask how much they should pay themselves after buying a business, they’re usually comparing that number to a salary, but that’s the wrong comparison to make. A salary is compensation for your time, and it can only move as fast as raises and promotions allow.
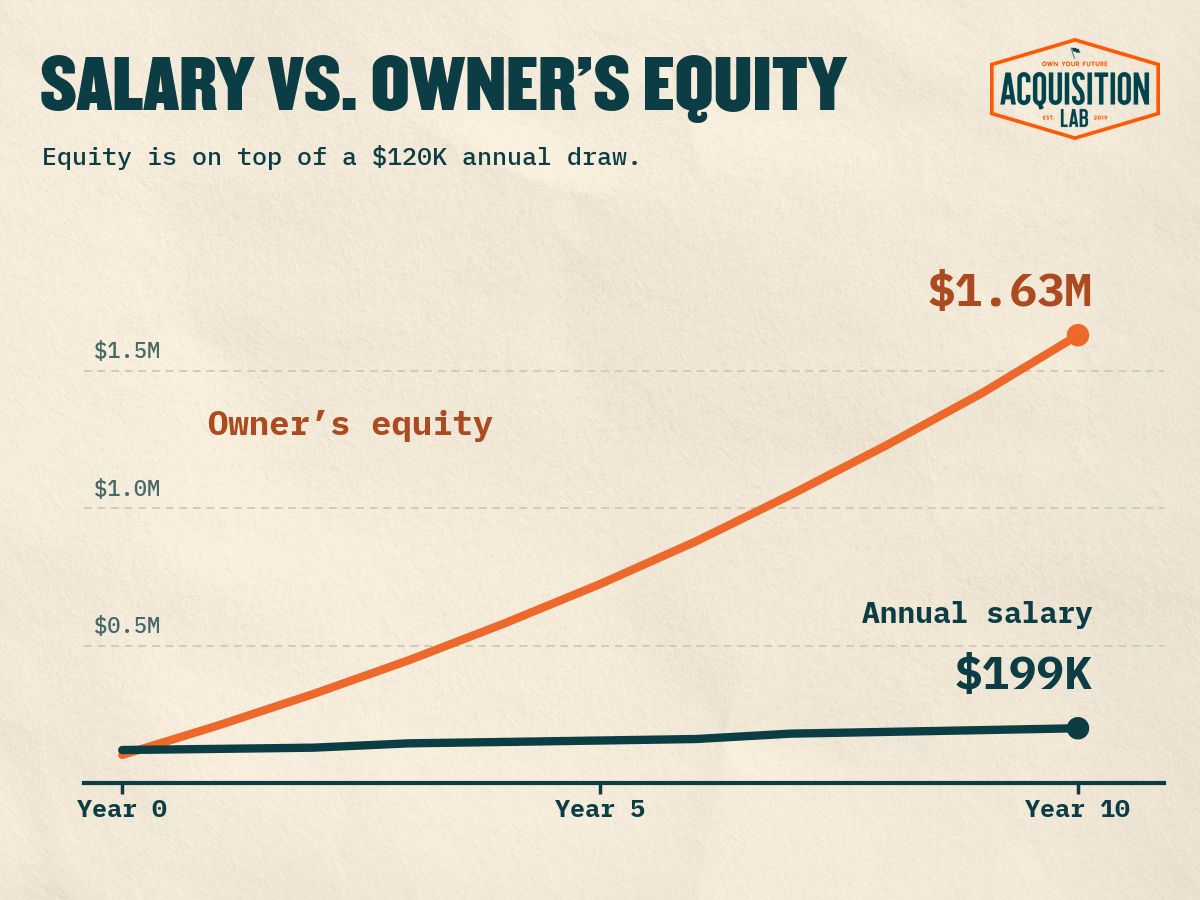
The Four Levers of Return
Ownership is a different mechanism entirely. It produces returns through four separate channels running at the same time: equity, cash flow, debt paydown, and exit. A salary is one line of compensation, and it moves only as fast as raises and promotions allow.
These four channels compound together instead, which is exactly what the chart above shows: one path moves in a straight line, the other bends upward. It isn’t that one path works harder than the other. It’s that one path only has a single lever to pull, and the other has four.
Equity ownership
When you own equity, you own a piece of the business itself, net of whatever debt is still owed against it. If you took out a loan to buy a business, you’ll also have an ownership claim against that debt.
That matters because equity is the major lever that turns ownership into wealth. The three levers depend on your equity stake in order to function. Cash flow needs a claim to flow into, debt paydown needs an asset underneath it, and an exit needs a claim to sell.
Example: Assume you buy a $1 million business with $100,000 down and $900,000 in financing. You don’t just own the portion of the business that’s worth $100,000. You own the entire $1 million asset, from the moment you close. Your equity, what’s actually yours net of debt, starts at $100,000. But you control, and have a claim on, the full $1 million from day one. That distinction is what makes debt paydown its own lever rather than just part of equity.
Income only becomes wealth once it’s saved and converted into something that holds value. When spent, it leaves nothing behind.
Employees can build real wealth through stock options and restricted stock units (RSUs). Once shares are vested and owned, they represent genuine equity in the company. That said, employee equity comes with limitations that distinguish it from owning and operating a business yourself.
- Vesting. RSUs generally have to vest before you receive the shares. If you leave the company early, you may forfeit some or all of your unvested equity.
- Exercise costs. Stock options give you the right to purchase shares at a predetermined price. Depending on the company’s value and the terms of the options, exercising them can require significant capital.
- Liquidity. Publicly traded shares are generally easier to sell, but private company equity can be difficult to convert into cash. Your shares may have substantial value without providing a practical way to access it.
- Control. Employee shareholders generally have little influence over company strategy, financial decisions, or the timing of an eventual sale. Your equity’s value largely depends on decisions made by someone else.
Employee equity can be valuable, but it generally makes you a participant in the company’s success rather than the person directing it.
Owning and operating a business gives you greater control over the decisions that determine its performance, along with the responsibility and financial risk that come with those decisions. It’s a direct claim on an asset, and a vehicle for wealth. Federal Reserve data shows families that own a business have higher income and wealth than families that don’t, and that gap widens with the size of the business.
Ownership carries real risk, with most of it concentrated in a single asset rather than spread across a portfolio and with no public market pricing it day to day. It’s a fundamentally different position when compared to employment, because you own an asset and aren’t being paid directly for the time you work on it.
Cash flow during ownership
A profitable business can generate income while you own it, separate from whatever you receive if you eventually sell.
For smaller businesses, one common measure of earnings is seller discretionary earnings (SDE). This starts with the business’s profit and adjusts for items such as interest, taxes, depreciation, amortization, one owner’s compensation, and certain discretionary or nonrecurring expenses.
SDE helps buyers understand how much a business earns before accounting for the cost of replacing the owner. However, it isn’t the same as cash available to take home. Debt payments, taxes, capital expenditures, working capital needs, and reinvestment can all reduce what an owner actually keeps.
Building on the example above: Assume your $1 million business generates $334,000 a year in SDE. Some of that $334,000 represents compensation for the work of running the business. If that work would cost $120,000 annually to replace with a general manager, approximately $214,000 remains before financing costs, taxes, capital expenditures, and other cash requirements.
SDE combines the economic benefit of ownership with the value of the owner’s labor. That’s why two businesses reporting identical SDE can produce very different financial outcomes depending on how they’re operated, financed, and managed.
Unlike a private equity fund that asks investors to wait four to seven years for a single payout, an owner-operated business can pay you the entire time you hold it, assuming that you have the cash flow to support a salary draw.
Here’s how that $334,000 from our example business breaks down:
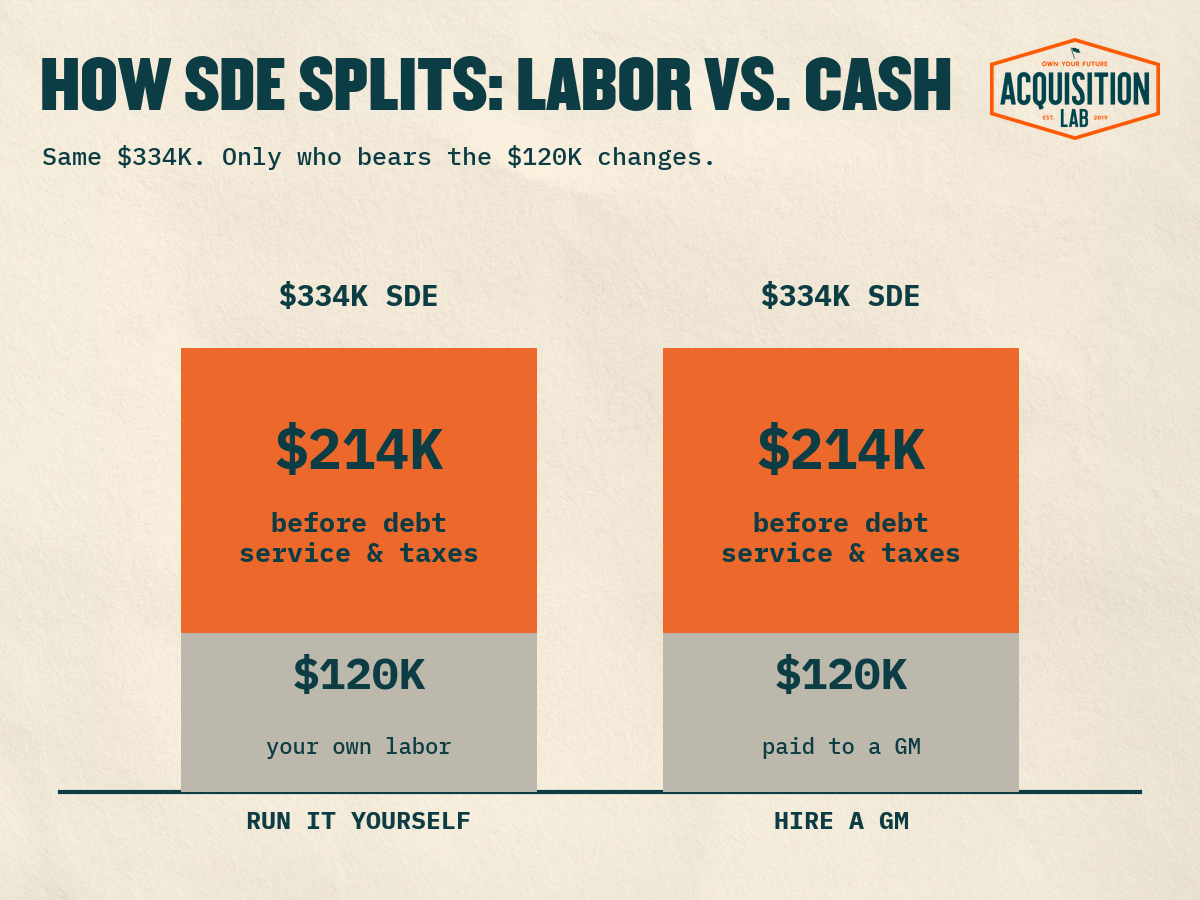
In either case, an employee doesn’t have this option. A salary is fixed pay for time worked. There’s no pool of company cash flow an employee gets to direct, no matter how well the company performs.
However, as a lever, cash flow competes with both itself and the other levers of ownership. Debt service and reinvestment both want a piece of that cash flow, and in the first year or two of ownership, there may not be much cash left over at all.
That competition isn’t a flaw, though. It’s a sign the cash flow is doing double duty. Every dollar that goes toward debt service isn’t lost; it’s working as its own lever entirely.
Debt paydown
Most acquisitions aren’t fully paid for in cash.
A buyer typically puts down a fraction of the purchase price — often 10% — and borrows the rest, usually through a bank loan (typically an SBA loan for U.S.-based buyers). That loan is a real debt, owed to a real lender, and it has to be paid back over time, just like a mortgage on a home.
However, there’s a major difference when buying a business: acquisition debt is generally intended to be repaid using the business’s cash flow rather than the owner’s personal earnings.
New owners don’t need to pay down that debt with their own paychecks, like they would with a home mortgage. The business generates revenue, and a portion of earnings are used to reduce the loan.
That’s how debt paydown works as a lever. As an owner, you’ll control the entire asset from the day you close. Debt repayment gradually increases the net value of your equity.
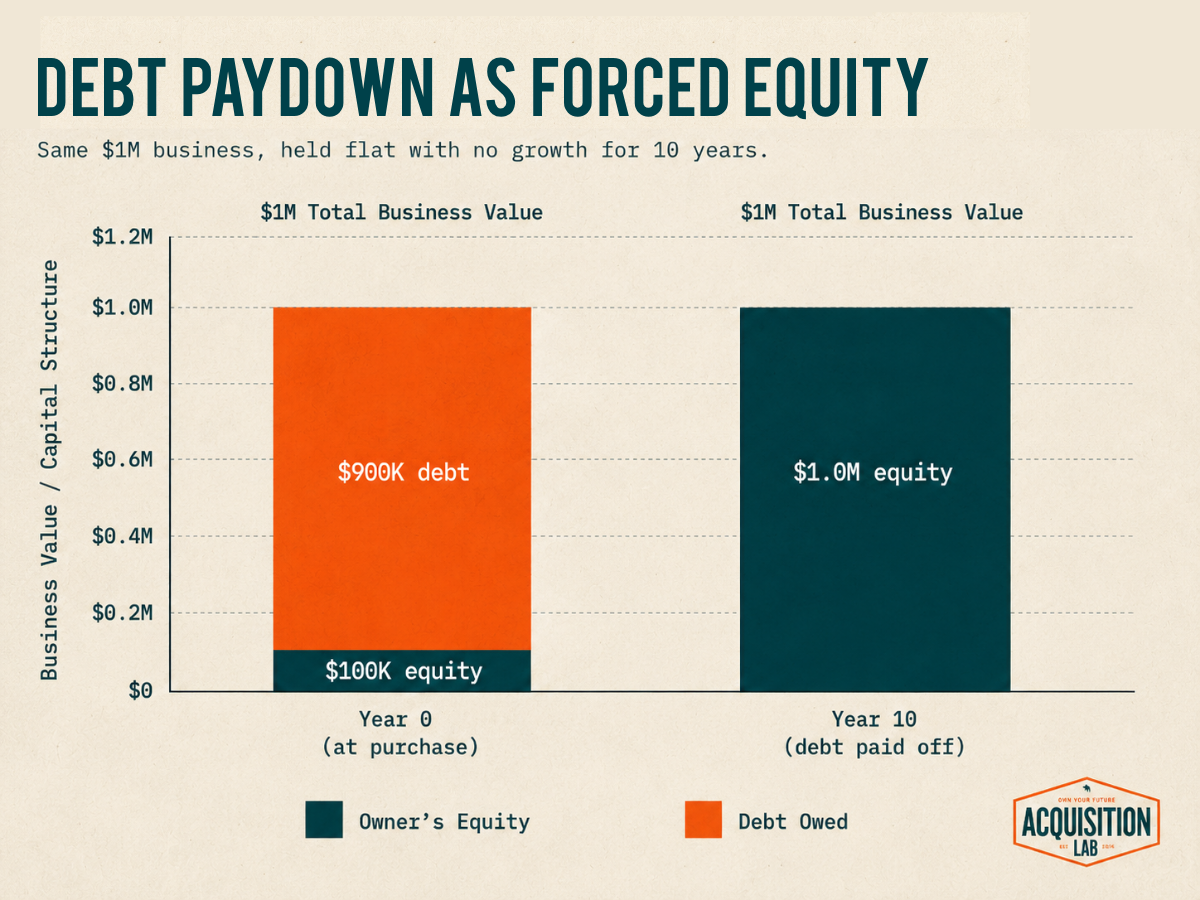
This process is called forced equity. As the business makes principal payments on its acquisition loan, the amount owed decreases, increasing the net value of your ownership even if the business itself doesn’t grow.
You’ll see that change by comparing the business’s estimated value with its remaining loan balance over time.
Building on the example above: Assume you buy a $1 million business with $100,000 down and $900,000 in financing. Let’s assume the business remains steady for ten years, generating $334,000 annually in seller discretionary earnings (SDE).
As the owner, you’ll need to draw a salary and keep cash in reserve to operate the business. Assuming you take $120,000 annually in compensation, that leaves $214,000 before debt payments and other cash requirements.
With a 9.5% interest rate and a 10-year loan term, your annual debt payments total roughly $140,000, leaving approximately $74,000 before taxes, additional reserves, and reinvestment.
Over ten years, the business pays off the acquisition loan through its own earnings. Assuming the company’s value stays at $1 million, your equity grows from $100,000 at purchase to $1 million once the debt is fully repaid.
As the business pays down its acquisition debt, your equity increases even if the value of the company stays the same. When the business generates enough cash to cover its loan payments, that debt gradually decreases without requiring additional contributions from your personal savings.
Employees can also build wealth by saving and investing their earnings. The difference with business ownership is that the asset’s own earnings can help repay the debt used to acquire it, building equity alongside whatever compensation you receive for running the company.
It’s worth pointing out that debts come with risks and caveats. Taking on more debt than the business can comfortably service is one of the most common ways searchers get themselves into trouble.
Debt paydown works when a profitable business can earn its way through the debt, not because debt itself is good.
Exit or transfer value
The exit is the event where a business gets sold and a multiple — the price stated as some number times its annual earnings — gets applied to determine what it sells for.
As a lever, the exit converts years of equity, cash flow, and debt paydown into a single event. It’s the closest thing that the ownership model has to cashing out a career all at once.
Building on the example above: Say you bought that $1 million business at a 3x multiple on $334,000 in SDE. If you sold it years later at that same 3x multiple with no growth at all, it would still be worth $1 million. However, debt paydown while you owned and worked in the business will have already converted much of that value into equity you keep.
Upon sale, your equity stake and the multiple would determine how much money you earn and what needs to be paid to close out the existing debt.
If you grow the business even modestly while you own it, the multiple will apply to a larger number, making the exit worth more than the business you originally bought.
At a 3x multiple, every additional dollar in annual earnings could support three dollars in additional business value, before accounting for debt, selling costs, and taxes. This isn’t because the deal terms changed, but because what you’re selling has changed.
An employee doesn’t get this moment. Years of raises and tenure never convert into a lump sum. The paycheck just stops when the work ends.
Debt paydown and overall growth will increase your earnings at exit, which is why the exit tends to be the largest single event in the whole return.
How ownership compounds value over time
A salary and business ownership can both help you build wealth. The difference is in where that growth comes from.
- Earned income. A paycheck gives you money to cover expenses, save, and invest. Money you invest can compound as the assets you own increase in value or generate returns.
- Business ownership. An acquired business can generate cash flow, pay down the debt used to buy it, and grow in value. As the loan balance falls or the business becomes more valuable, your equity can increase.
Those processes can reinforce each other. Cash generated by the business may fund improvements that increase future earnings. Stronger earnings can support debt payments and improve the business’s eventual sale value.
But there is no guarantee that every business will grow or produce enough cash to do all three.
Compounding takes time
In the first few years of ownership, a large share of the company’s earnings may need to go toward loan payments, working capital, or unexpected expenses. You may take home less than you did in your previous job, even when the business is performing well.
Someone earning $120,000 annually and consistently investing part of that salary can build substantial wealth during the same period. Ownership isn’t automatically a faster path.
Over time, a healthy business may create more financial flexibility. As acquisition debt is paid down, your equity increases. If earnings grow, the business may become more valuable and provide more cash for compensation or reinvestment. These gains can build on one another, but setbacks can slow or reverse them.
The opportunity isn’t that a business owner can compound wealth and an employee cannot. It’s that ownership provides additional ways to build value through an asset you directly operate and influence.
How the Four Levers work together
The Four Levers work together to build wealth through ownership. Each plays a different role, but the value they create is connected. As a business grows, generates cash, and pays down debt, the owner’s financial position can improve in several ways at once.
- Equity ownership. Your equity represents the portion of the business’s value that belongs to you after accounting for debt. As the business grows in value and its debt decreases, your equity can increase without requiring additional money from your personal savings.
- Cash flow. A profitable business generates cash that can support owner compensation, repay debt, or fund improvements. Reinvesting some of that cash can increase future earnings, creating more cash flow to put toward those same priorities.
- Debt paydown. Every principal payment reduces what the business owes and increases the equity you hold, assuming the business maintains its value. As the loan balance decreases, more of the business’s value belongs to you free and clear.
- Exit or transfer value. When you eventually sell, the business is valued based on what it has become, not what you originally purchased. Growth and higher earnings can support a larger sale price, even if your valuation multiple stays the same. After repaying any remaining debt and covering sale costs, the remaining proceeds belong to the equity owners.
Business growth strengthens these levers rather than forcing them to operate separately. Higher earnings can produce more cash flow, support faster debt repayment, and increase the value of your equity at exit.
That’s how ownership can build wealth through several connected mechanisms over time, rather than relying on increases in compensation alone.
Ownership: 5-year example
Everything above is the theory. Here’s what it looks like worked out in actual numbers using a common, realistic scenario.
Starting assumptions
- Purchase price: $1,000,000 (3x starting SDE)
- Starting SDE: $334,000
- Down payment: $100,000
- Financing: $900,000 SBA loan, 9.5% interest, 10-year term
- Annual growth: 5%
- Hold period: 5 years
- Exit multiple: 3x (same multiple paid at purchase)
- Owner’s annual draw: $120,000
Some points to note in this example:
Interest Rate: We’re using lending rates for when this article was originally written, not the lower historical rates you’ll sometimes see in illustrative examples elsewhere. That makes this example conservative rather than cherry-picked, and it means the numbers below only get better for a buyer if rates come down. Every figure that follows is reproducible from the assumptions above; nothing is hidden.
Hold Period: Five years is a reasonable middle ground. This period is long enough for debt paydown and modest growth to meaningfully change the numbers but short enough to stay grounded rather than reaching for a dramatic, decade-plus scenario.
Annual Growth: 5% annual growth is deliberately modest. It’s not a projection that requires a turnaround story or an aggressive growth plan to hit — just steady, ordinary performance.
Owner’s Draw: The $120,000 draw is the same figure used in the salary comparison earlier in this piece, so the two paths can be compared on equal footing later on.
Returns during ownership
At purchase, this business generates roughly $334,000 a year in seller discretionary earnings (SDE).
- Year five SDE: roughly $426,000, with 5% annual growth
- Owner’s draw: $120,000 a year, flat across all five years, totaling $600,000
- Remaining cash flow: available to service debt, reinvest, or add to what you keep at sale
That draw is fixed and doesn’t grow the way a salary might through raises or promotions. Every dollar of upside beyond that $120,000 a year comes from the other three levers, not from the business paying you more to run it.
Equity through debt paydown
At the same time cash flow is growing, the $900,000 loan balance is shrinking.
- Loan terms: $900,000 at 9.5% over a 10-year term
- Principal paid down: roughly $345,000 over the first five years
- Remaining balance: about $555,000
The paydown happens using the business’s own earnings, not money out of your pocket, and it converts directly into equity you own outright.
Combined with the business’s growth, your equity position moves from a $100,000 down payment to roughly $725,000 by year five — the $1.28 million the business is now worth minus the $555,000 still owed on it.
That’s before the sale itself even happens.
Value at exit
If you sold the business in year five, its larger earnings base could support a higher sale price than what you originally paid.
In our example, five years of 5% annual growth takes SDE from $334,000 to roughly $426,000. Applying the same 3x multiple used at purchase gives the business an estimated sale value of $1.28 million.
But the sale price isn’t what you take home. You still have to repay the remaining acquisition debt, which stands at approximately $555,000 after five years. You also have to account for your original investment and distinguish the proceeds from selling the business from the compensation you earned while operating it.
Here’s how those numbers come together.
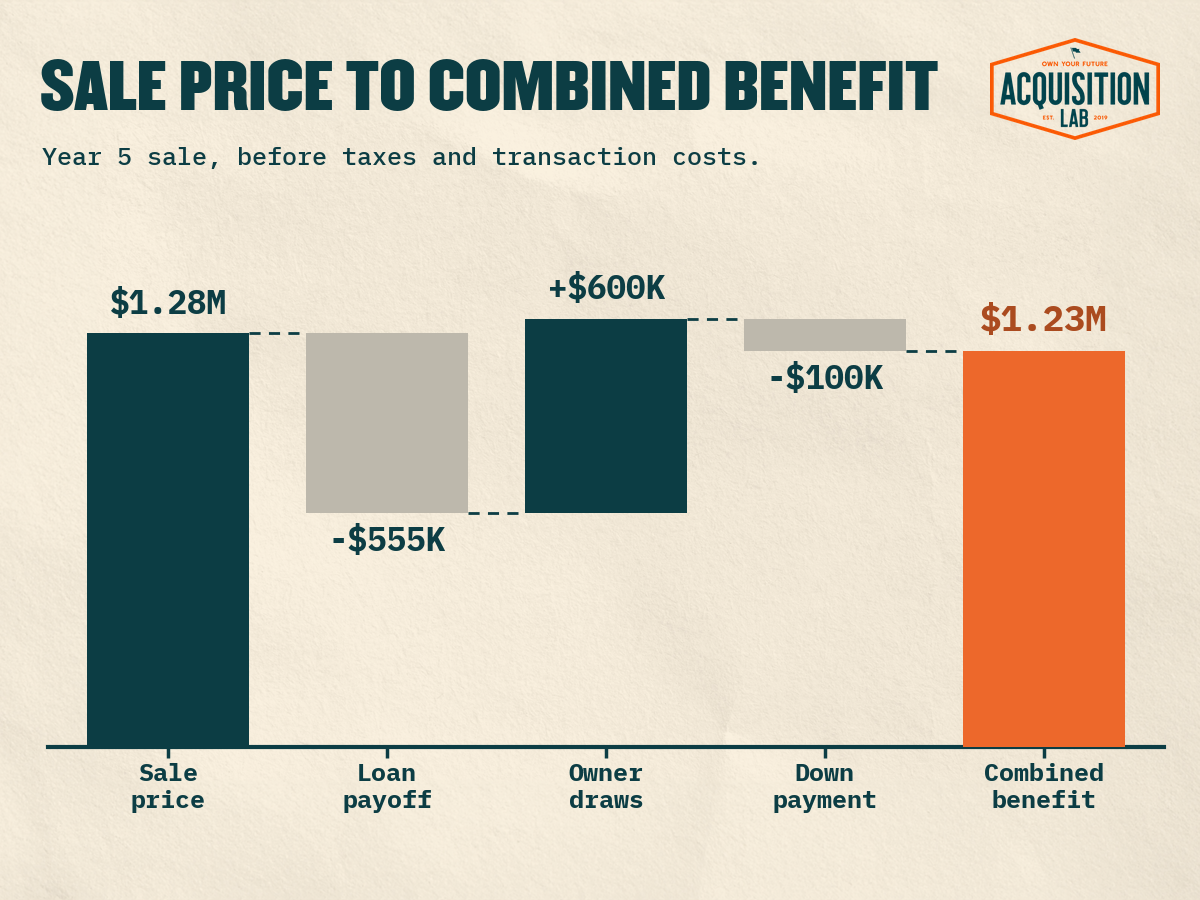
The final figure includes two different sources of value: the gain on your original investment and five years of compensation for running the business. Both benefit the owner financially, but they aren’t equivalent to an investment return.
This example assumes a sale in year five to illustrate how the financial mechanics work together. Most owners aren’t buying with a fixed exit date in mind. They’re buying a business they intend to operate, improve, and potentially hold for many years.
The actual outcome will depend on the business’s performance, the amount of debt remaining, and when — or whether — the owner eventually sells.
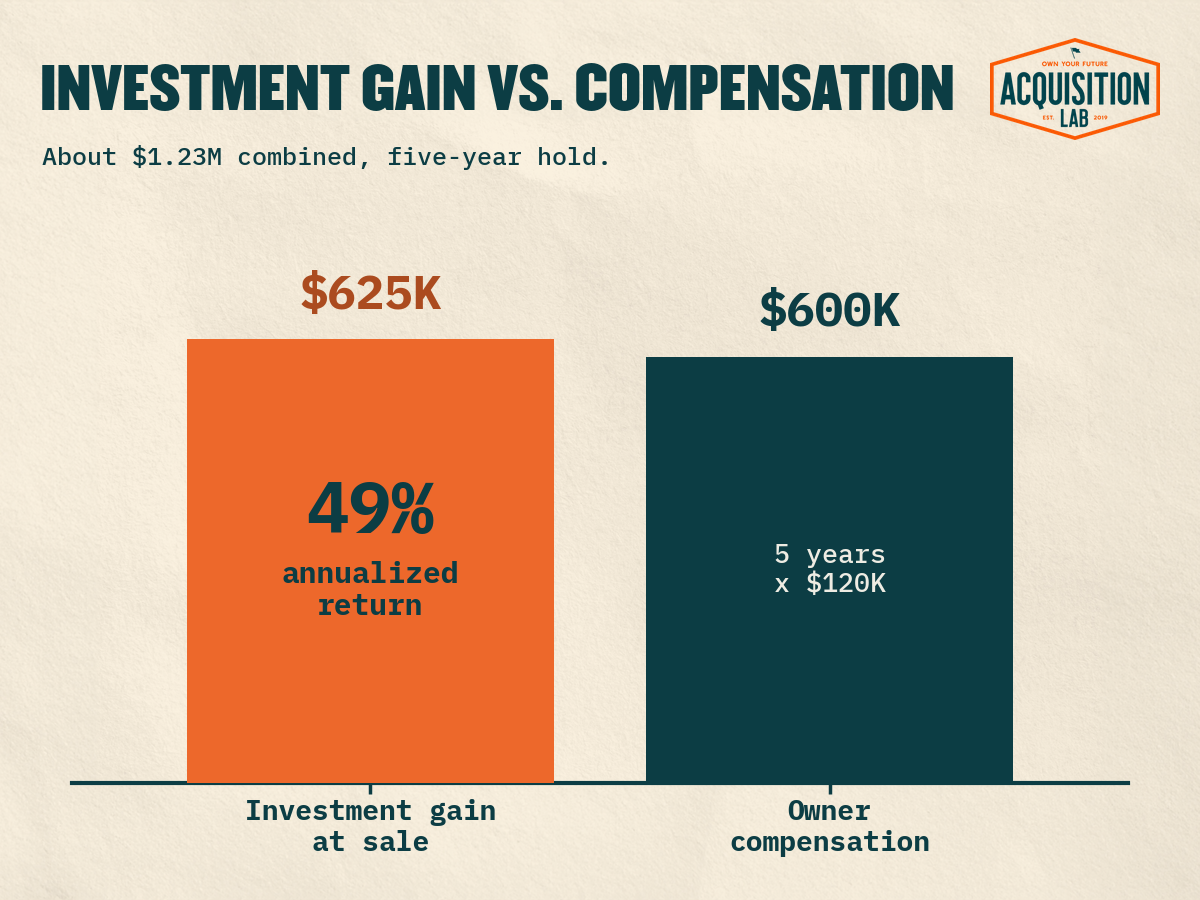
Value breakdown: ownership returns vs. compensation
The combined financial benefit above includes both investment gains and compensation for running the business. It’s worth separating those two amounts, because they represent different kinds of financial value.
At year five, the business sells for approximately $1.28 million. After paying off the remaining $555,000 loan balance, the owner receives roughly $725,000 from the sale. Subtract the original $100,000 down payment, and the investment has generated approximately $625,000 in gains.
Measured as an investment alone, the $100,000 down payment became roughly $725,000 in equity at sale, about 7x the original cash and an annualized return near 49%, before taxes and transaction costs. That’s at 5% annual growth, which is deliberately modest. Most of the return comes from leverage and debt paydown, not from the business growing fast.
These figures are illustrative and exclude taxes, transaction costs, and any additional capital the owner may have needed to contribute.
What can affect ownership returns
Everything covered so far describes what happens when the entire ownership process works as intended. It’s worth being just as direct about what can make it fail, because each of the Four Levers depends partially on conditions that are out of your direct control.
Business performance
The math throughout this piece describes what happens when a business is run well, but performance is never guaranteed. If the business underperforms, every lever slows down. That means less cash flow to distribute, slower debt paydown, and a smaller number at exit.
Lab member David Graf bought a business with the numbers already working in his favor, and grew adjusted earnings by 58% in under two years, largely by tightening how the business managed its inventory and cash conversion cycle. That growth came from the operating decisions he made, not from any feature of the deal itself.
The reverse is just as true: a business bought well can still underperform in the hands of an owner who runs it poorly.
How to reduce this risk:
- Buy a business with a track record long enough to judge, not just a good story.
- Have a real operating plan before you close, not just a financial model.
- Stay close enough to the numbers that underperformance shows up early, not a year later.
Purchase price & margin of safety
Every return in this calculation is based on the original purchase price. Overpay, and the same business produces a worse return on every lever at once, not just one.
Optimistic assumptions about growth, margin, or how quickly a business will improve can justify almost any price on paper, which is exactly the problem: the assumptions end up doing the work of making a deal look better than it is.
A higher purchase price usually means more debt, too, which raises the stakes on the leverage risk below at the same time.
How to reduce this risk:
- Favor a business with a real growth trend already in place over a mature one you’re hoping to reignite.
- Conduct preliminary screening before making an offer, and complete full due diligence before closing.
- Set your own walk-away price and margin of safety before you’re emotionally invested in a specific deal.
Leverage & personal guarantees
Many acquisition loans, particularly SBA-backed financing, require buyers to personally guarantee the debt. If you’ve signed a personal guarantee, you may remain responsible for unpaid amounts even if the business fails.
This is common because lenders aren’t inclined to loan millions of dollars against a business and let borrowers walk away with no consequences if something goes wrong. If the business fails, that debt doesn’t stay inside the LLC. It follows you.
SBA default rates remain historically low relative to startup failure rates, but that’s a claim about the financing surviving, not about your business specifically. It says nothing about whether any individual business performs the way a model assumes it will.
How to reduce this risk:
- When taking on debt, look at what the business can comfortably service based on current performance, not projected earnings.
- Keep a real cash buffer separate from what you need to cover debt service.
- Understand exactly what you’re personally on the hook for before you sign, not after.
Concentration & liquidity
Ownership carries real risk that’s structurally different from owning a diversified investment portfolio. Most of your capital is concentrated in a single asset, and there’s no public market pricing it day to day.
You can’t sell 10% of a business on a bad week the way you could sell shares of a stock.
This is also why the multi-year time horizon matters. These levers realize value over years, not months, and anyone expecting fast liquidity from this model is in the wrong vehicle.
How to reduce this risk:
- Don’t commit capital you might need access to on short notice.
- Go in expecting a multi-year hold, not a quick turnaround.
- Understand that your net worth will be concentrated in this one asset for a meaningful stretch of time.
Exit uncertainty
None of this is guaranteed, though. Your anticipated sale value can move as the business grows or shrinks, as market conditions shift, or as buyer timelines slip past what you’d planned for.
And a meaningful share of small businesses never sell at all, whether because no buyer materializes at the price a seller wants, the business isn’t in sellable shape when the owner is ready to exit, or the owner simply keeps running it rather than transacting.
How to reduce this risk:
- Don’t build your plan around a specific exit multiple or timeline.
- Run the business as if you’ll hold it indefinitely, so its value doesn’t depend on a sale happening on schedule.
- Treat an eventual sale as a “someday,” not a fixed date you’re managing toward.
Check for understanding
Before moving on, you should be able to answer each of these. If you can’t, the section to revisit is noted next to it.
- What’s the real difference between income and wealth? (How Ownership Turns Work Into Wealth)
- What are the Four Levers of Return, and what does each one do? (The Four Levers of Return)
- Why do the four levers compound instead of just adding up? (How Ownership Compounds Value Over Time)
- Why is it worth separating the investment gain from the owner’s compensation? (Ownership: A Five-Year Example)
- What are the main categories of risk that can reduce or eliminate these returns? (What Can Affect Ownership Returns)
A few terms worth having solid before moving on:
- SDE (seller discretionary earnings): a business’s total cash flow before subtracting a salary for whoever runs it day to day.
- Hold period: the length of time you own the business before selling or transferring it.
- Multiple: the price of a business stated as some number times its annual earnings.
- Forced equity: equity created automatically as debt gets paid down, without you saving or writing a check for it.
If any of these don’t come easily, that’s a signal to go back, not a failure. The Four Levers framework discussed here is the one piece of this worth carrying with you past this article. Concepts in future guides will build on it.
Up next
The Four Levers framework appears throughout the Learn library. This article lays the foundation, but there’s more to explore.
From here, the natural next step is Buy, Build, Franchise, or Invest?, where we get into how buying an existing business compares to starting one, franchising, or investing passively, so you can figure out which path to ownership actually fits you.
Guide 002 — Deciding Buy, Build, Franchise, or InvestReady to keep going?
- The SBA’s own guide to 7(a) loans covers the mechanics of the financing itself, if you want more detail on how the debt piece of this actually works.
- SCORE’s guide to determining a fair owner replacement salary is useful if you want to go deeper on the SDE question raised earlier in this piece, what a business would actually cost to run without you.
➔ What to Read and Listen to Next collects books, podcasts, and real acquisition stories to keep learning from.
FAQ
Why does ownership build wealth differently than earning a salary?
A salary pays you for your work. Business ownership can build wealth through four channels: equity growth, cash flow, debt paydown, and an eventual sale. Together, these create opportunities to accumulate wealth beyond what you earn from working.
Is owning a business better than earning a high income?
They serve different purposes. A high income supports your lifestyle and savings, while ownership gives you an asset that can generate cash flow, appreciate, and eventually be sold. Ownership offers greater potential upside, but also carries financial and operational risks.
What’s the difference between income and wealth?
Income is money you earn over time. Wealth is the value of what you own minus what you owe. Income can help build wealth when saved and invested, but earning a high salary doesn’t automatically translate into a high net worth.
Why is equity more valuable than compensation?
Equity represents ownership in an asset that can appreciate, generate cash flow, and eventually be sold. Compensation pays you for work performed. Unlike a paycheck, equity can continue building value over time, although that value is never guaranteed.
Does ownership always outperform employment?
No. Ownership creates opportunities to build wealth beyond a salary, but results depend on the purchase price, business performance, financing, and eventual exit. A poorly purchased or operated business can destroy wealth rather than create it.
What risks come with business ownership?
The main risks include poor business performance, overpaying, acquisition debt and personal guarantees, concentrated wealth in an illiquid asset, and uncertainty around selling. Each can reduce or eliminate the financial benefits of ownership.